What the Bank of Canada's September Rate Hold Means for Metro Vancouver Buyers
The Bank of Canada held its policy rate at 2.25 percent on September 2, 2026, its seventh straight decision without a change. Borrowing costs did not move this week. What matters more for buyers is why, and what it signals next.
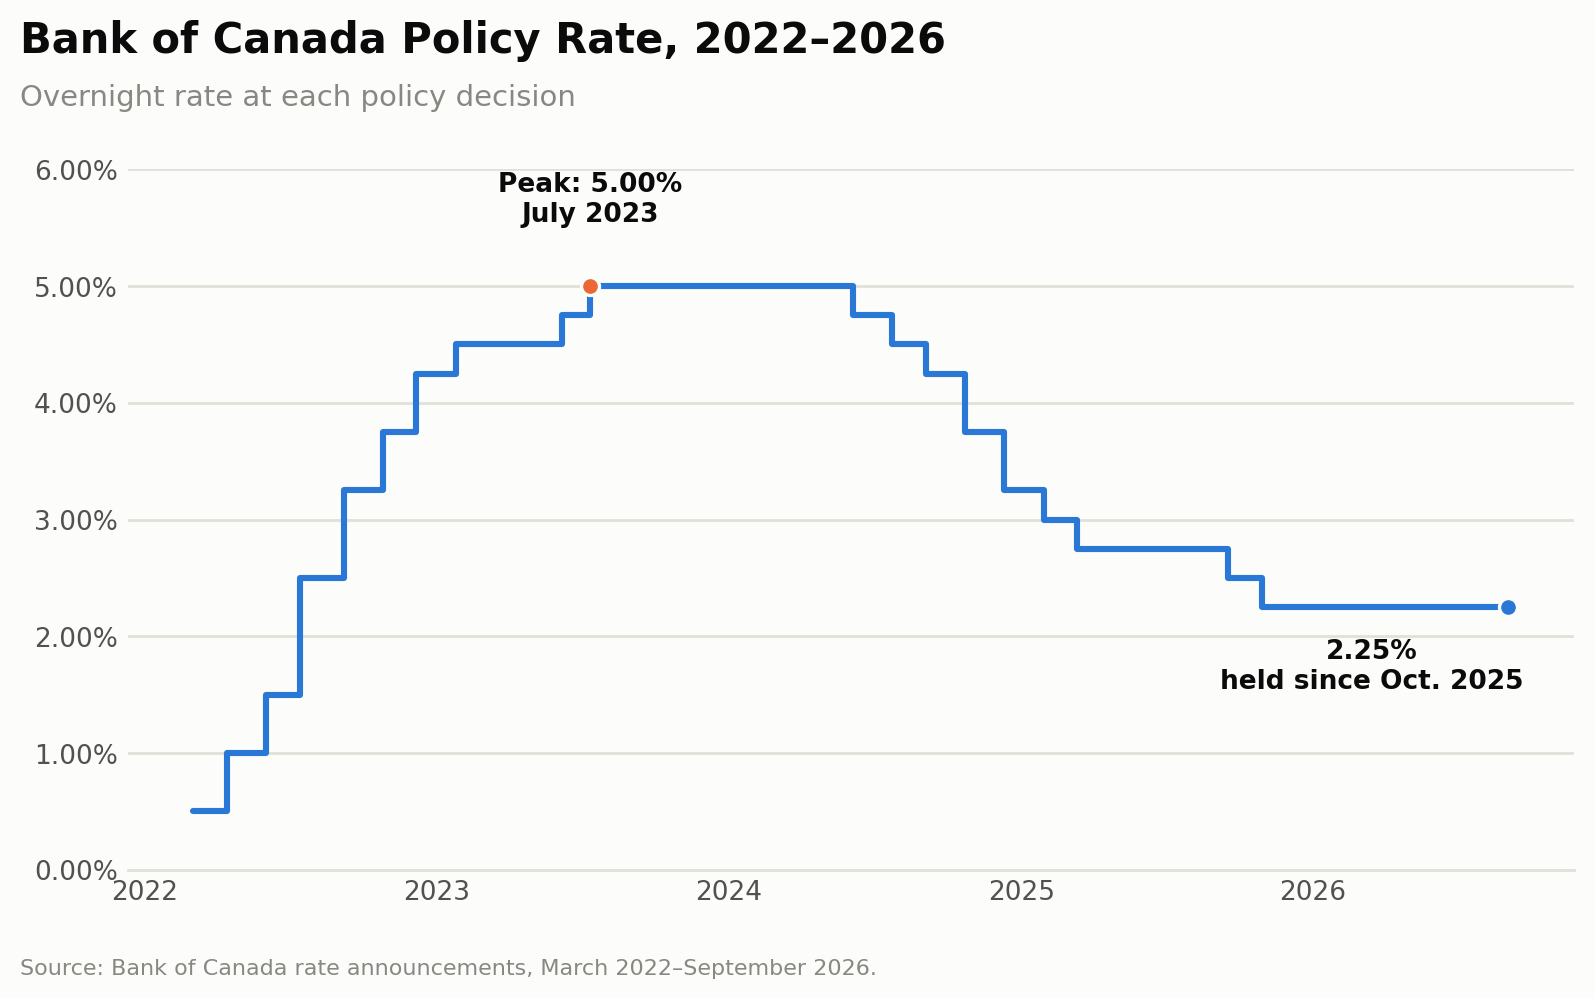
This chart shows the full cycle: ten hikes between March 2022 and July 2023 took the rate from 0.50 percent to a peak of 5.00 percent, based on the Bank's own announcement history. Cuts starting June 2024 brought it to 2.25 percent by October 2025, where it has held since.
This time the reasoning was mixed. Canada's economy grew 3.3 percent in the second quarter of 2026 and unemployment eased to 6.4 percent in July, stronger than expected, according to the Bank's September statement. At the same time, tariffs and Middle East-driven oil prices have pushed headline inflation toward 3 percent, even as core inflation (which strips out volatile items like gas) sits closer to the Bank's 2 percent target. The Bank said it is prepared to raise rates again if tariff-driven costs spread further into everyday prices, a firmer warning than a routine hold usually carries. The next scheduled decision is October 28, 2026.
What this means for your mortgage
A held policy rate does not mean a held mortgage rate: lenders price off bond yields and competition. As of September 2, 2026, the best available high-ratio 5-year fixed rate in Canada was 4.09 percent and the best 5-year variable was 3.30 percent.
The stress test still applies either way: insured mortgages qualify at the higher of your contract rate plus 2 percentage points, or a 5.25 percent floor unchanged since June 2021, so it remains the binding number for most buyers — your approved amount is set against a rate higher than what you'd actually pay, worth confirming with your lender before setting a price range.
The Bank's warning that it's "prepared to raise rates again" is worth weighing in a fixed-versus-variable choice: fixed locks in certainty for your term, variable is cheaper today but more exposed if a hike lands before renewal. It's a reasonable moment to raise with your mortgage broker rather than defaulting to last year's choice.
If you're comparing pre-approval numbers or want a second read on how this affects your budget, reach out to discuss your situation.